
Credit Scores Explained in Plain English

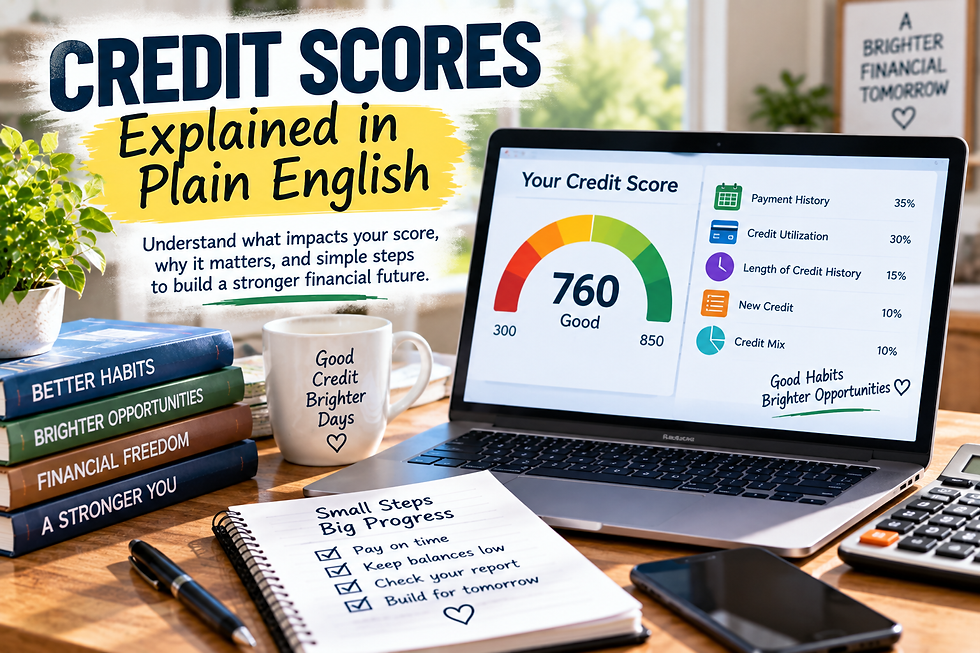
Your credit score can affect many financial decisions, from applying for a credit card to borrowing money for a car or home. Yet the number can feel confusing, especially when different companies show slightly different scores.
A credit score is simply a number designed to help lenders estimate how likely you are to repay borrowed money as agreed. Understanding what goes into that number can make credit feel much less mysterious.
What Is a Credit Score?
A credit score is calculated using information from your credit history. In the United States, many commonly used credit scoring models produce scores ranging from 300 to 850.
Generally, a higher score indicates that your credit history suggests lower lending risk. A lower score may make borrowing more difficult or result in less favorable terms.
Your score is not a measure of your income, wealth, or overall financial success. It focuses primarily on how you have managed credit.

Payment History Matters
Whether you pay your bills on time can have a significant influence on your credit score.
Late or missed payments on accounts reported to credit bureaus can negatively affect your credit history. Paying credit obligations by their due dates can help you establish a record of reliable repayment.
Setting up reminders or automatic payments can make due dates easier to manage.

Credit Card Balances Can Affect Your Score
Credit scoring models may consider how much of your available revolving credit you are using. This is commonly called credit utilization.
For example, if your credit card has a $5,000 limit and your reported balance is $1,000, you are using 20% of that available credit.
Lower balances relative to your available limits can generally be better for your credit profile than consistently using most of your available credit.
The Age of Your Credit History Counts
The length of your credit history can also influence your score.
Older accounts can provide more information about how you have handled credit over time. This does not mean you should keep every account open forever, but closing an older account may affect your overall credit profile.
Consider the account's fees, benefits, and your financial needs before deciding whether to close it.

New Credit Applications Can Have an Impact
When you apply for certain types of credit, a lender may perform a hard inquiry on your credit report. Hard inquiries can affect your score, although their impact varies.
Applying for several accounts within a short period may have a greater effect than occasionally applying for credit when you need it.
Checking your own credit generally does not count as a hard inquiry.
Different Scores Can Be Normal
You do not necessarily have one universal credit score.
Different lenders may use different scoring models, versions, or credit bureau information. That means the score you see through a bank or credit monitoring service may not exactly match the score a lender uses.
A small difference does not automatically mean something is wrong.
Final Thoughts
Credit scores can seem complicated, but the basic idea is straightforward. They use information from your credit history to help lenders evaluate borrowing risk.
Paying bills on time, keeping credit card balances manageable, being thoughtful about new applications, and reviewing your credit reports for accuracy can support a healthier credit profile. Instead of focusing on achieving a perfect number, concentrate on consistent credit habits that can serve you over time.
Comments